No single company is top rated for every borrower. The useful move is to compare a broker’s wholesale access against national direct lenders on the same loan scenario, using soft-pull quotes before any hard credit inquiry. This list is for active rate-shoppers. The companies were chosen on four points: the loan types they offer, how they quote rates, whether you work with a person or an app, and how clearly they disclose costs. Duane Buziak starts the list with his own free comparison tool because it is built to be the first stop, before a lender runs a hard pull on your credit. The CFPB’s owning a home resources also encourage comparing multiple offers.
At-a-Glance Comparison of the Companies
- Free Mortgage Search by Duane Buziak: active rate-shoppers who want to compare before any hard pull; free to use, with loan rates and fees quote-based; compares offers across hundreds of wholesale lenders in one search without a hard credit inquiry.
- Rocket: borrowers who want to apply mostly online; quote-based, see its website; a self-service digital experience at national scale.
- Movement: purchase buyers who want a named loan officer; quote-based, see its website; relationship-based, loan-officer-led guidance through a purchase.
- NFM Lending: borrowers who prefer branch or in-person contact; quote-based, see its website; a branch-level, local-feeling support model.
- Guild Mortgage: buyers weighing renovation or specialized purchase financing; quote-based, see its website; wide financing conversations led by a loan officer.
- Veterans United: service members and veterans using VA loan benefits; quote-based, see its website; a process built around military and veteran borrowers.
1. Free Mortgage Search by Duane Buziak
Free Mortgage Search by Duane Buziak is a free comparison tool backed by broker independence. Duane Buziak is a broker, not a bank, so he is not limited to one company’s shelf. He can compare offers from hundreds of wholesale lenders against your scenario. Helping buyers find the right mortgage since 2014 is the thread behind the tool: show people real options first, then let them choose.
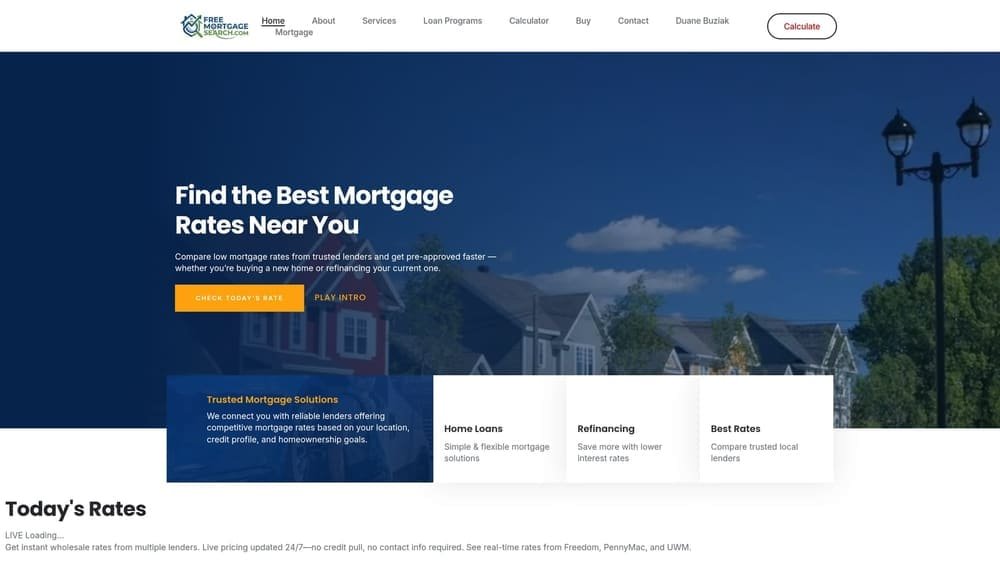
What sets it apart on this list is the order of operations. The NoTouch Credit Pull runs a soft-pull comparison, so you can see how offers stack up without a hard inquiry landing on your report. Every other company here prices from its own shelf, which makes it a natural second or third quote to hold up against what the tool returns.
- Free rate comparison across wholesale lenders, so you see a spread of offers rather than one company’s number.
- NoTouch Credit Pull lets you compare using a soft pull, keeping your score clear of a hard inquiry until you pick a direction.
- Dare to Compare reviews a Loan Estimate you already hold from another company, line by line, so you can see how the rate, points, and fees measure up.
- Purchase and refinance guidance covers rate lock periods and timing, not just a quote.
- Title services keep a closing task under the same roof as the loan.
There are no third-party integrations to claim. Setup is a short intake, and Duane Buziak personally guides the file from comparison through closing. The limitations are plain. It is a broker model, so there is no single branded app and no in-house servicing; the loan you choose is funded and serviced under the wholesale lender’s name. And licensing is limited to VA, FL, TN, GA, DC, NC, SC, and MD, so borrowers in other states cannot use it.
Pricing: the comparison is free to use. Loan rates and fees are quote-based, driven by credit profile, down payment, loan amount, property type, and lock period, and all costs appear on your Loan Estimate.
Best for: Active rate-shoppers who want to compare before any hard pull.
2. Rocket
Rocket is a large national direct lender known for a digital-first application. It is designed for borrowers comfortable handling most of a mortgage on a screen, from the first application through document collection. Check its website for current loan programs and state availability, since those details change.

Its distinctive strength on this list is self-service at national scale. If you would rather upload paperwork at 10 p.m. than schedule a call, the process is built around that preference. That same design is the trade-off for borrowers who want a person walking them through each decision.
- Online application lets you start and complete the request without a phone call.
- Digital document upload replaces emailing and faxing pay stubs and statements.
- Purchase and refinance loans cover the two most common reasons to borrow.
- Online account tracking shows where your file stands so you are not chasing status updates.
Integrations and setup details are best confirmed on its website. Day to day, you run most of the file yourself online, with support available when you need it. The main limitation is structural: Rocket prices only its own shelf. A single quote tells you what that company offers, not how it compares, so hold the Loan Estimate next to others, including through Dare to Compare. It is also a weaker fit if you want a long, personal advisory conversation.
Pricing is quote-based. Rates and costs move with credit score, down payment or equity, loan amount, loan type, and lock period. See its website for current details.
Best for: Borrowers who want to apply mostly online with minimal phone contact.
3. Movement
Movement is a national retail lender that works through local loan officers. It is designed for buyers who want a specific person to answer questions, review a pre-approval, and coordinate with the agent and the closing table. Confirm current products and state coverage on its website.

The standout here is relationship-based guidance through a purchase. A named loan officer can be valuable when a contract has tight deadlines, because the same person knows your file from start to finish.
- Loan-officer-led process gives you one contact to call rather than a queue.
- Purchase and refinance loans let you stay with one company if your needs change.
- Online application option means you can still begin digitally and hand off to a person.
- Pre-approval guidance helps you understand what you can shop for before you make offers.
See its website for integrations and technology details. The loan officer runs the process day to day, with you supplying documents. The limitation is single-lender pricing. Whatever the loan officer quotes comes from one company’s rate sheet, so the Loan Estimate should be compared elsewhere before you commit. Borrowers whose priority is a quick, hands-off online process may find the personal-contact model more involved than they want.
Pricing is quote-based, and it shifts with credit profile, loan size, down payment, property type, and rate lock length.
Best for: Purchase buyers who want a named loan officer guiding the process.
4. NFM Lending
NFM Lending is a retail mortgage lender with branch-based loan officers. Its model suits borrowers who like the idea of a nearby office and a face-to-face conversation. Verify its headquarters and licensed states on its website before assuming it serves your area.
What it does distinctively well compared with the rest of the list is branch-level, local-feeling support. Where Rocket leans on the app and Movement on a named loan officer, NFM Lending’s emphasis is on the branch as the point of contact.
- Branch-based loan officers let you meet in person or work with people who know your market.
- Purchase and refinance loans cover the most common borrowing goals.
- Online application gives you a digital starting point alongside the personal contact.
- Pre-qualification support helps you understand a realistic budget before you shop.
Integrations are listed on its website. Setup is typically a conversation with the branch followed by an application and document collection, with the loan officer coordinating the file. The limitation is that it offers one lender’s shelf, so it is not suited to pricing across many lenders in a single search. Experience can also vary from branch to branch, so ask who will handle your file. Borrowers who want to compare many offers before talking to anyone will find a comparison tool a better first step.
Pricing is quote-based and depends on credit, down payment, loan amount, loan type, and lock period. Ask for a written Loan Estimate to compare.
Best for: Borrowers who prefer branch or in-person contact.
5. Guild Mortgage
Guild Mortgage is a national retail lender with a large network of loan officers. It is designed for buyers who expect to talk through their financing, especially when the purchase involves more than a standard conventional loan. Verify its current product range on its website.
The distinctive part, compared with the others here, is the breadth of purchase and renovation financing conversations led by a loan officer. If you are buying a home that needs work, or you are weighing a less common structure, a loan officer can walk through whether it fits.
- Loan-officer network puts a person in front of you who can explain program differences.
- Purchase and refinance loans cover standard borrowing needs.
- Renovation financing (verify current availability) lets you fold repair costs into one loan rather than financing them separately.
- Online application speeds up the start of the process.
Check its website for integrations. A loan officer runs the file day to day, and renovation loans generally involve more paperwork and timeline coordination than a standard purchase, so allow for that. The limitation is the single-company shelf. Even with a wide menu, you see one lender’s pricing, so compare Loan Estimates before you commit. Borrowers who want only a fast, app-driven process may find the conversation-heavy approach slower than they prefer.
Pricing is quote-based. Credit, down payment, loan amount, property type, and the program you choose all move the rate and costs.
Best for: Buyers weighing renovation or specialized purchase financing with a loan officer.
6. Veterans United
Veterans United is a lender that specializes in VA home loans for service members and veterans. It is designed for that community, and its process, education, and support are built around military borrowers. Verify its current loan menu on its website, including any conventional options.
The standout is focus. Where the other companies serve a general audience, this one organizes its whole process around military and veteran borrowers, which can help if you want guidance specific to those benefits. For one example, the VA funding fee has its own rules, which are explained on VA.gov.
- VA loan specialization means staff are used to the paperwork and terminology that comes with the benefit.
- Conventional options (verify current availability) may give you a second route if your situation changes.
- Online application lets you start the process digitally.
- Military-focused support addresses questions that general lenders may not hear every day.
See its website for integrations. A loan team runs the file, and you supply service documentation and financial records. The main limitation is relevance: it is less useful for borrowers outside the military community, and like every direct lender here, it prices from one shelf. Even eligible borrowers can benefit from lining up its Loan Estimate against another quote.
Pricing is quote-based, and rates and costs move with credit profile, loan amount, down payment, property type, and program.
Best for: Service members and veterans using VA loan benefits.
A Worked Example: What a Quarter Point Is Worth
This example is an illustration only, not a quote. Suppose you are borrowing $400,000 on a 30-year fixed loan, and two Loan Estimates come back for the same scenario. Offer A is 6.50%, and Offer B is 6.25%.
- Offer A principal and interest: about $2,528 per month.
- Offer B principal and interest: about $2,463 per month.
- Difference: about $65 per month, or about $785 per year.
- Over five years: about $3,925, before taxes, insurance, and any fee differences.
Now suppose Offer B carries $2,000 more in upfront costs. Divide $2,000 by $65.40 and you get roughly 31 months to break even. If you expect to keep the loan beyond that, Offer B wins; if you plan to sell or refinance sooner, Offer A may. That is why the rate alone is not enough. The Loan Estimate shows points, lender fees, and cash to close side by side, and the CFPB’s Loan Estimate guide explains how to read each section. If a loan fits under conforming loan limits, the FHFA publishes the current figures; as of October 2026, confirm the 2026 limit there rather than relying on an older number.
How a Broker’s Access Differs From a Single Company’s Shelf
- Pricing sources: a broker like Duane Buziak can compare offers from hundreds of wholesale lenders; a direct lender prices from its own rate sheet.
- Credit impact: a NoTouch Credit Pull comparison is a soft pull; a direct application typically begins with a hard inquiry.
- Contact model: a broker is one point of contact across many options; direct lenders offer an app, a loan officer, or a branch, depending on the company.
- Servicing and branding: a brokered loan is funded and serviced by the wholesale lender; a direct lender can fund and service in house.
- Checking an outside quote: Dare to Compare lets a broker review a Loan Estimate from any company against comparable scenarios.
Questions Borrowers Ask Before Comparing Mortgage Companies
Which mortgage company is top rated?
None is top rated for every borrower. The right company depends on your loan type, how you like to work, and how its Loan Estimate compares with others on the same scenario.
Does comparing mortgage quotes hurt my credit?
A soft-pull comparison does not. The NoTouch Credit Pull lets you compare offers without a hard inquiry. Applying directly with a lender typically involves a hard pull, so soft-pull comparison first keeps your options open.
What is the difference between a mortgage broker and a direct lender?
A broker compares offers from many wholesale lenders. A direct lender funds loans from its own shelf and usually services them too. Neither is automatically cheaper, which is why comparing matters.
Is Free Mortgage Search by Duane Buziak really free?
Yes. Comparing offers costs nothing. Loan costs, if you proceed, appear on your Loan Estimate.
What does Dare to Compare do?
You bring a written Loan Estimate from another company, and Duane Buziak reviews it against a comparable scenario so you can see where the rate, points, and fees stand.
Which states does Duane Buziak serve?
Licensed states are VA, FL, TN, GA, DC, NC, SC, and MD. If you are elsewhere, one of the other companies here may be the better path.
I am a first-time buyer. Where do I start?
Start by deciding your budget and how much guidance you want. Then request a soft-pull comparison, ask for written Loan Estimates, and compare the same loan amount, term, and lock period. A loan officer or broker can explain anything that looks unfamiliar.
Should I compare a lower rate or lower costs?
Compare both, plus how long you will keep the loan. A lower rate with higher upfront costs pays off only after a break-even period, as the worked example above shows.
Which Company Fits Which Borrower, and a Calm Next Step
Three picks stand out by situation. If you are rate-shopping and want to see many offers without a hard inquiry, Free Mortgage Search by Duane Buziak is the logical first stop. If you want an app-first process, Rocket fits, and if you want a named loan officer through a purchase, Movement fits. Borrowers who like a local branch can look at NFM Lending, buyers with renovation plans can talk to Guild Mortgage, and service members using VA benefits should include Veterans United in their comparison.
Whichever direction you lean, there is no deadline to decide. Run a NoTouch Credit Pull comparison, or bring a written offer to Dare to Compare, and look at the numbers side by side. Your dream home is within reach: start comparing personalized mortgage rates from trusted lenders today and discover the loan solution that fits your budget and goals. Compare rates now and take the first step toward securing your home with expert guidance every step of the way from Free Mortgage Search by Duane Buziak.